
The Notification Gap: Why Most People Never Hear Their Money Was Escheated
States are required to attempt owner notification before taking custody of funds — but these efforts often fall short. Here's why so many claims go undiscovered.
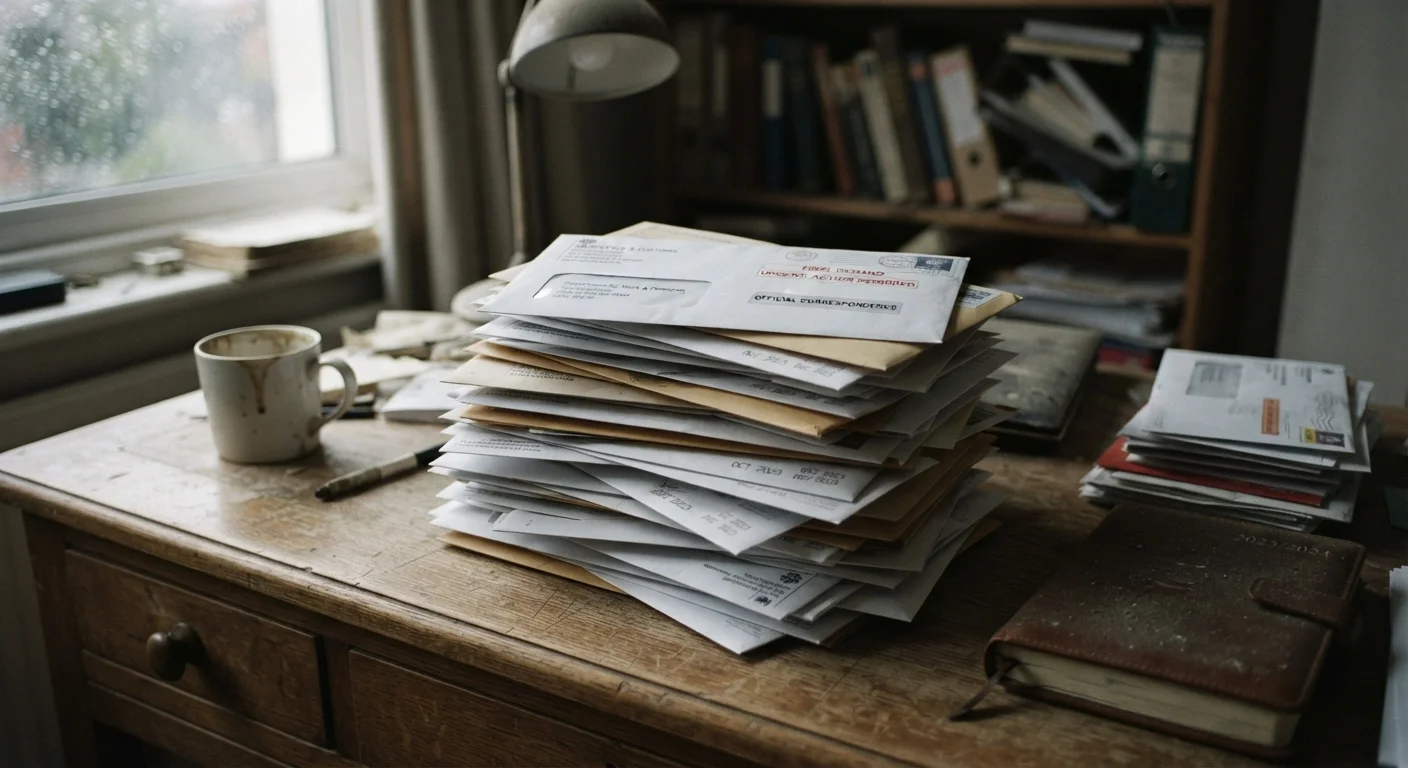
Photo: searchopenrecords editorial
—— In This Article
Key Takeaways
- States are legally required to attempt owner notification before escheating funds, but those efforts often fail to reach the actual owner.
- Outdated contact information held by financial institutions is the leading reason notices go undelivered.
- Newspaper publication, a common notification method, is largely ineffective for modern audiences.
- Funds escheated to state custody remain searchable and claimable indefinitely in most states.
- Proactively searching official databases is far more reliable than waiting for a government notice.
What the Law Actually Requires
Before any dormant account is transferred to state custody, the law imposes a notification duty — but understanding what that duty actually entails reveals why it so frequently falls short.
Under most state unclaimed property statutes — many of which draw from the Uniform Unclaimed Property Act — the holder (the bank, insurance company, or brokerage holding your funds) must send a written due-diligence notice to the owner's last known address. This notice is typically required when the dormancy period is within a set window before the transfer deadline, often one to two years in advance.
After funds are remitted, states publish owner information in official databases and, in many jurisdictions, in local newspapers. This satisfies the state's statutory publication requirement. What it does not do is guarantee the actual owner is informed. To understand why, it helps to follow the money — see how dormant funds move from private hands to public record for the full journey.
Why Notices Miss Their Mark
The notification process has several structural vulnerabilities that compound over time.
Outdated Address Records
The single biggest reason notices go undelivered is stale contact information. Financial institutions use the address on file when an account was opened or last updated — which could be decades old. Americans move frequently; the average person relocates more than ten times over a lifetime. An institution holding a dormant account opened at age 22 may still have a college dormitory address on file for a 55-year-old.
Institutional Mergers and Account Transfers
When banks merge or are acquired, customer records migrate across systems — and contact data often degrades in the process. The institution remitting your escheated funds may have inherited your account from two or three predecessor banks, each of which had its own recordkeeping standards.
Low-Visibility Publication Methods
Newspaper publication was a reasonable public notice mechanism in an earlier era. Today, it reaches a narrow audience. Most people do not read legal-notice sections of newspapers, and many jurisdictions publish notices only once. Online database listings are more durable, but only help owners who know to look.
Notices Can Look Like Junk Mail
Even when a due-diligence notice successfully reaches the correct address, recipients often mistake it for promotional mail or a phishing attempt and discard it unopened. If you receive any official correspondence about a dormant or inactive financial account, open it before discarding — legitimate institutions and state agencies do send these notices, and they require a response to prevent escheatment.
Even when a notice is successfully delivered, research on consumer behavior suggests that official-looking mail about dormant financial accounts is frequently mistaken for junk mail or phishing attempts and discarded without being opened.
The Scale of the Notification Gap
$70B+
Total unclaimed property held by U.S. states
According to the National Association of Unclaimed Property Administrators (NAUPA), U.S. states collectively hold more than $70 billion in unclaimed property at any given time.
1 in 10
Americans estimated to have unclaimed property
NAUPA has estimated that approximately one in ten Americans has unclaimed property listed in a state database, though many are unaware of it.
11.7 times
Average number of times Americans move in a lifetime
U.S. Census Bureau data indicates Americans move an average of 11.7 times over their lifetime, making address-based notification increasingly unreliable for long-dormant accounts.
The aggregate result of these failures is substantial. State unclaimed property programs collectively hold tens of billions of dollars in assets at any given time — a figure that grows each year as new accounts lapse into dormancy faster than existing claims are resolved.
Importantly, this is not evidence of government wrongdoing. States are holding these funds on behalf of rightful owners, not absorbing them. As explained in why unclaimed money doesn't disappear, the custodial model exists precisely to preserve owner rights. But custodianship only helps owners who know to claim what's theirs.
What This Means for You as a Potential Owner
The practical takeaway from the notification gap is straightforward: do not wait to be contacted. The system is not designed to find you — it is designed to preserve your ability to find it.
Proactive searching through official portals is the only reliable method. Many people are surprised to learn that funds they had no idea existed are listed in their name. Common sources include forgotten security deposits, insurance policy payouts, old utility refunds, and uncashed dividend checks.
Several search habits lead to missed unclaimed property — including searching only your current name or only your current state of residence. Former names, maiden names, and states where you previously lived or worked are all worth checking. The official state database search guides walk through how to run a thorough, multi-state search at no cost.
It is also worth dispelling a common misconception: many people assume that because they never received a notice, there is nothing to find — or that the funds have expired. Neither is true. See common misconceptions that stop people from searching for a full breakdown of these myths.
Once you locate a listing, the next step is filing an official claim. The claims process involves identity verification and documentation, but for most straightforward claims it can be completed without professional help. Be aware that certain documentation issues can slow the process — common pitfalls that delay or derail legitimate claims are worth reviewing before you apply.
This article is for general informational purposes only and does not constitute legal, financial, or tax advice. For questions specific to your situation, consult a qualified professional.
Frequently Asked Questions
Unclaimed Money Editorial Team
Unclaimed Money Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile