
The Life of a Forgotten Dollar: How Unclaimed Money Moves from Private Hands to Public Record
Trace the full journey of dormant funds — from untouched bank accounts to state custody — and understand why governments hold this money on your behalf.
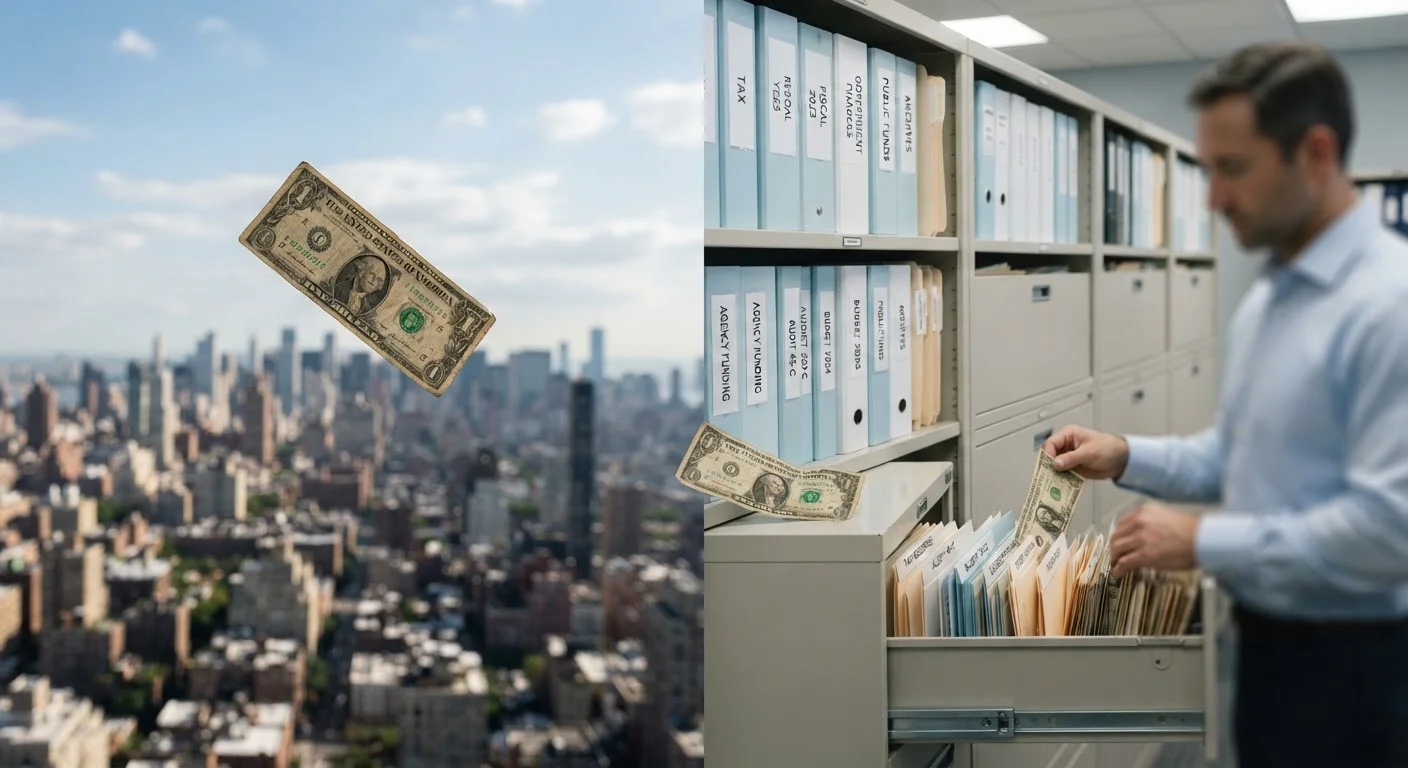
Photo: searchopenrecords editorial
—— In This Article
Key Takeaways
- Unclaimed money doesn't vanish — it moves to state custody under a legal process called escheatment.
- Holders like banks and insurers must report and transfer dormant assets to the state after a set dormancy period.
- States are required to make unclaimed property searchable in public databases.
- Rightful owners can claim their funds at any time — there is generally no deadline.
- The process is governed by state law and exists to protect owners, not to permanently seize their assets.
Stage One: A Dollar Goes Quiet
Every piece of unclaimed money starts with a simple act — or rather, an absence of one. An account sits untouched. A paycheck goes uncashed. A refund check gets buried in a drawer. These are ordinary oversights, but over time they trigger a formal legal sequence.
State laws define a dormancy period — a window of inactivity after which an asset is considered abandoned. For a standard bank savings account, this is commonly three to five years. For uncashed payroll checks, it may be as short as one year. The clock typically starts from the last point of owner-initiated contact: a login, a deposit, a reply to a statement, or a written instruction. Simply receiving a bank statement does not reset the clock in most states.
Understanding what qualifies as dormant is the first step. Explore the full range of asset types governments hold, which extends well beyond bank accounts to insurance policies, pension distributions, and even security deposits.
Stage Two: The Holder's Legal Obligations
Once dormancy thresholds are met, the institution holding the funds — called a holder — takes on specific legal duties. Holders include banks, credit unions, life insurance companies, brokerage firms, employers, and utilities. They are not permitted to quietly absorb the money into their own revenues.
Before transferring anything to the state, most holders are required to make a due diligence attempt to locate the owner. This typically means mailing a notice to the last known address within a specified timeframe before the reporting deadline. If the owner doesn't respond, the holder proceeds with reporting.
Holders then submit an annual report to the state — disclosing every qualifying dormant account — and remit the funds to the state treasurer. Failure to comply can result in audits and financial penalties. This mandatory reporting cycle is what ensures dormant money doesn't simply disappear into a company's balance sheet.
$70B+
Estimated unclaimed property held by U.S. states
NAUPA (National Association of Unclaimed Property Administrators) estimates total state-held unclaimed property exceeds $70 billion across all 50 states.
1–5 years
Typical dormancy period before escheatment
Most state laws set dormancy periods between one and five years depending on the property type, with bank accounts commonly set at three to five years.
Indefinite
Duration states must hold unclaimed funds
In most U.S. states, rightful owners or their heirs may file a claim at any time — there is no statute of limitations on recovering escheated cash.
Stage Three: Escheatment and the Transfer to Public Record
The formal transfer of funds from a holder to the state is called escheatment. Despite the archaic sound of the word, the modern process is protective by design: the state receives the money not as its own but as a custodian acting on behalf of the rightful owner.
Once funds are escheated, the state is required to make them discoverable. Property records are entered into searchable public databases — typically maintained by the state treasurer or comptroller — and also submitted to national aggregators like MissingMoney.com, which is operated in partnership with the National Association of Unclaimed Property Administrators (NAUPA). This is the moment a forgotten dollar becomes public record.
For a broader look at what happens to funds after this point, see why unclaimed money doesn't disappear once escheated.
Stage Four: Finding and Claiming What's Yours
With funds now in state custody and listed in a public database, the rightful owner — or their heirs — can initiate a claim. There is generally no expiration date on this right. States are required to hold the funds until a valid claim is made, making it possible to recover money that has sat dormant for decades.
The process involves searching an official database, identifying your property, and submitting a claim with documentation that proves your identity and ownership. Depending on the state and the amount involved, this can be straightforward or require additional verification steps.
To navigate the search process, start with official state database guides. When you're ready to file, step-by-step claiming guides walk through exactly what documents and timelines to expect.
For a detailed end-to-end view of what happens between dormancy and a successful payout, review the full timeline of the unclaimed funds process.
This article is for general informational purposes only and does not constitute legal or financial advice. For questions specific to your circumstances, consult a qualified professional.
Frequently Asked Questions
Unclaimed Money Editorial Team
Unclaimed Money Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile