
Privacy in the Digital Age: How Online Aggregators Change the Picture
Data aggregator sites compile public records into detailed profiles. Here's what that means for personal privacy and what the law does — and doesn't — say.
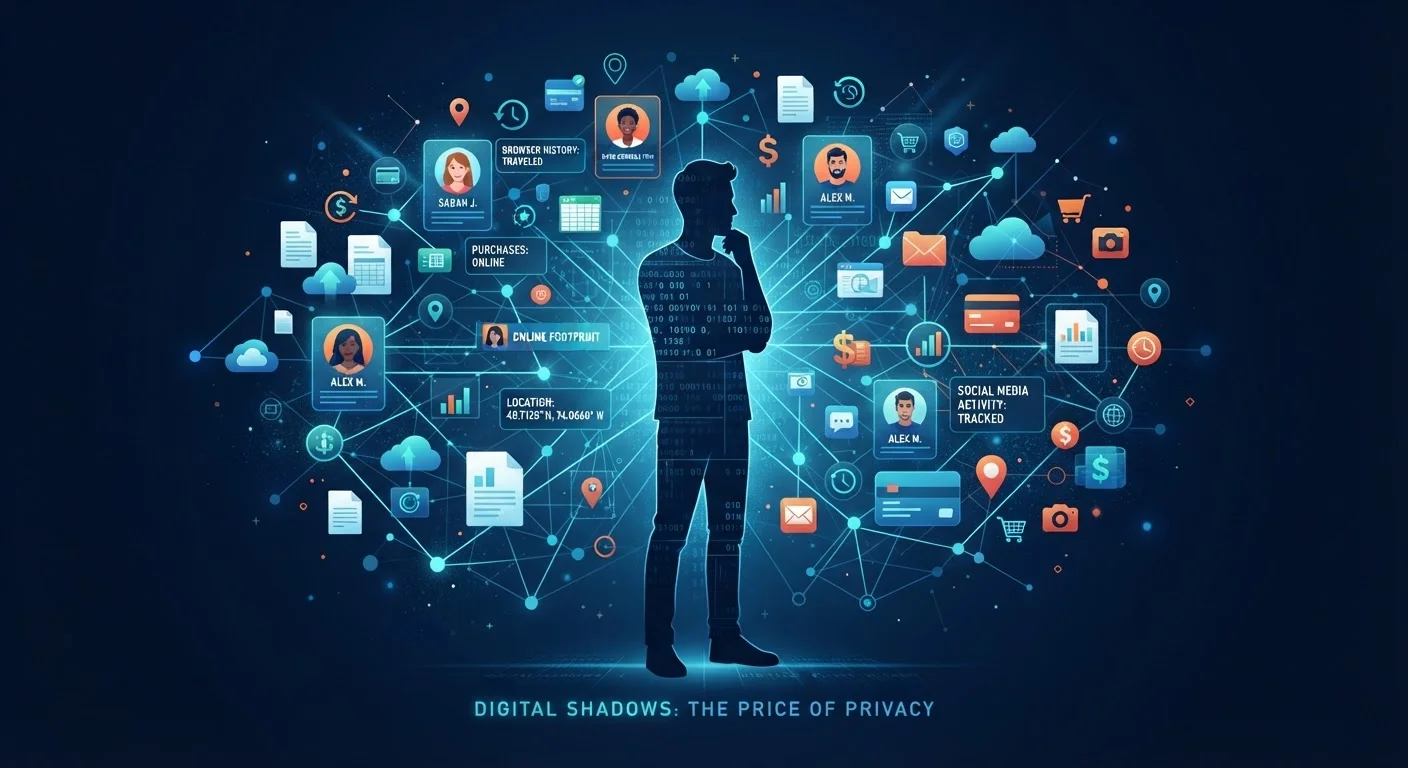
Photo: searchopenrecords editorial
—— In This Article
Key Takeaways
- Data aggregators combine individually public records into detailed personal profiles.
- The act of aggregation can reveal far more than any single record would on its own.
- Federal law does not comprehensively regulate data brokers; protections vary significantly by state.
- Most states offer opt-out or deletion rights, but the process is often fragmented and burdensome.
- Aggregators used for employment, credit, or housing decisions must follow FCRA rules.
From Scattered Records to Instant Profiles
Public records have always existed — court filings, property deeds, marriage licenses, and voter registrations are deliberately made available so that government activity remains transparent and accountable. For most of American history, accessing any one of these records meant visiting a courthouse, submitting a written request, or paying a clerk. The effort involved was, itself, a practical privacy shield.
The internet removed that friction almost entirely. Digitization of public records made government databases searchable, but it also enabled a new industry: data aggregation. These companies harvest information from dozens of public sources and merge it into a unified profile. What once required hours of effort at multiple agencies can now be retrieved in seconds by anyone with an internet connection.
This shift is significant not because any single piece of information is secret — it usually isn't — but because of what researchers call the aggregation problem. Your name is harmless. Your employer is harmless. Your neighborhood is harmless. But combine your name, employer, neighborhood, relatives, physical description, and daily routine, and you have a surveillance-grade profile assembled from entirely public data.
What the Law Does — and Doesn't — Protect
Federal law does not comprehensively regulate data brokers or aggregators. The primary federal statute that touches this space, the FCRA, applies only when data is used for specific "permissible purposes" — credit decisions, employment screening, insurance underwriting, or tenant evaluation. If an aggregator sells data for any other purpose — say, general curiosity — it largely falls outside FCRA oversight.
Privacy laws shaping online searches such as HIPAA and FERPA carve out medical and educational records, respectively. But aggregators generally work with data that is already publicly filed — property records, civil court judgments, business registrations — and those records carry no federal privacy shield once disclosed.
State law is where meaningful protections increasingly live. California's Delete Act, Vermont's data broker registry law, and similar statutes in Texas and Oregon require brokers to register with state authorities and, in some cases, honor consumer deletion requests. The patchwork nature of these laws means your rights depend heavily on where you live.
Aggregation and FCRA Compliance Are Separate Questions
Just because information comes from public records does not mean the report compiling it is FCRA-compliant. If you are subject to a background check for employment, housing, or credit, you have specific rights under the FCRA — but those rights apply only to reports from covered consumer reporting agencies, not to general data broker profiles. Always verify which type of report was used before attempting to exercise dispute rights.
Understanding the distinction between public-record data and protected private data matters when evaluating any report. Our article on public records vs. private data in background checks explains how that line is drawn in practice.
The Aggregator vs. Government Portal Distinction
Not all online record sources work the same way. Official government portals — maintained by courts, county clerks, and state agencies — provide access to original records, typically with defined access rules and, in some jurisdictions, redaction of sensitive fields. Third-party aggregators repackage that data and frequently append additional sources, including commercial databases, that government portals never contained.
That distinction matters for accuracy as well as privacy. Aggregated profiles can contain outdated information, records belonging to people with similar names, or data that was legally expunged from its original source but was captured before the expungement occurred. The differences between government portals and third-party aggregators are worth understanding before relying on either source.
For decisions that carry real consequences — employment, housing, lending — the law requires that consumer reports come from FCRA-compliant sources that maintain accuracy standards and provide dispute rights. Aggregator sites that disclaim FCRA compliance are, by definition, not appropriate for those uses. This is a legal boundary, not just an ethical preference.
What You Can Actually Do About It
Awareness is the starting point. Knowing that aggregator profiles exist and understanding their limits helps you evaluate information you encounter about yourself or others more critically. It also helps you identify when a data-driven decision — such as a background check for a job — should be scrutinized for accuracy.
If you want to reduce your aggregated footprint, most major data broker sites publish opt-out instructions in their privacy policies. Submitting individual opt-out requests is time-consuming, but it is the primary mechanism available to most Americans outside of states with stronger statutory rights. Residents of states with comprehensive consumer privacy laws — California, Colorado, Connecticut, Virginia, and others — may be able to submit a single verified deletion request that covers multiple brokers operating in that state's framework.
For accuracy disputes related to formal background checks, the FCRA gives you the right to request a copy of any report used against you, dispute inaccurate information, and receive a response within a defined timeframe. Those rights apply only to FCRA-covered reports — another reason the rights and accuracy framework matters in practice.
Finally, the broader tension between public transparency and individual privacy is a genuine and unresolved policy debate. Courts and lawmakers continue to weigh in. The line between public interest and personal privacy is actively contested territory, and the rules governing it will likely continue to evolve as technology outpaces legislation.
Frequently Asked Questions
Public Records 101 Editorial Team
Public Records 101 Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile